Lagos State has unveiled a long-term development plan targeting an economy worth nearly $1 trillion by 2052, with investments in infrastructure, manufacturing, technology and human capital expected to drive growth and strengthen its position as a global business hub.
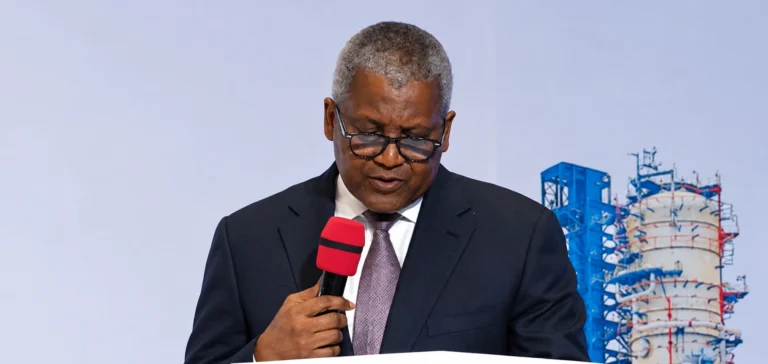
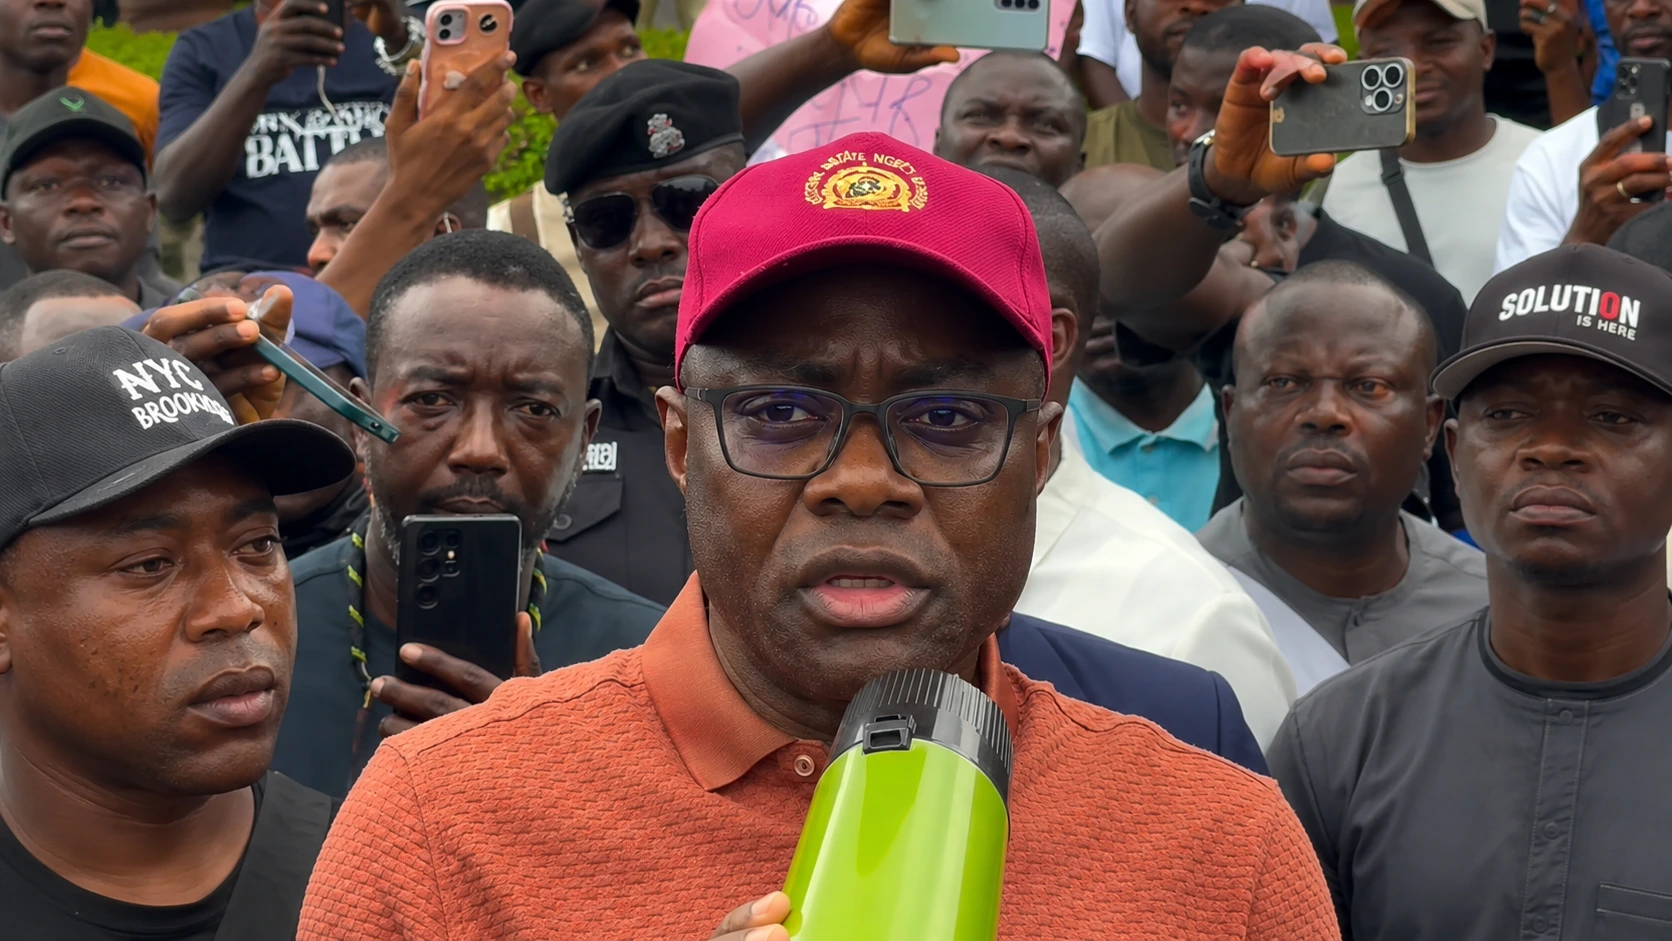
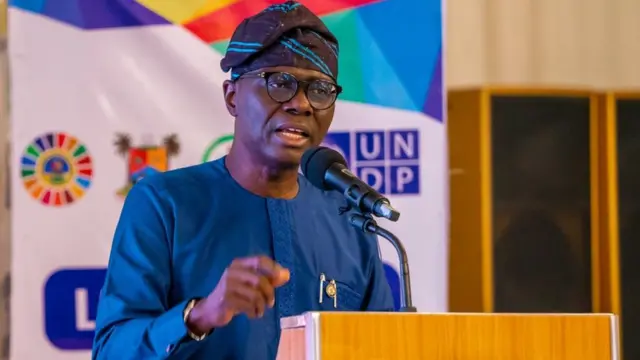
Governor Babajide Sanwo-Olu announced the ambition on October 28, 2026, at the Lagos Executive Business Breakfast Meeting organised by the Nigerian-British Chamber of Commerce (NBCC) in Lekki, Lagos.
The Lagos State Development Plan 2052 contains 447 initiatives spanning 21 strategic sectors, structured around four pillars: a thriving economy, a human-centred city, modern infrastructure and effective governance.
Sanwo-Olu said the plan was designed to attract domestic and foreign investment, support businesses and improve residents’ quality of life while positioning Lagos as a model African megacity.
Speaking at the meeting, themed “The Future of Lagos: Business, Investment and Global Competitiveness,” the governor highlighted infrastructure development, technological innovation and human capital as critical to achieving the state’s long-term economic ambitions.
Focus on Infrastructure, Technology and Manufacturing
The development plan prioritises improvements in port efficiency, manufacturing capacity and technological innovation to stimulate economic activity, create jobs and strengthen the state’s competitiveness.
Key projects include the expansion of the Blue and Red rail lines, electricity regulation and wider digital connectivity. The government also plans to strengthen healthcare and education to improve public services and develop a skilled workforce.
The Lekki Deep Sea Port and associated industrial developments are expected to play important roles in expanding regional trade, attracting investment and supporting manufacturing.
The state is also looking to grow its technology and creative industries, while supporting small and medium-sized enterprises through financing, grants and initiatives designed to encourage innovation.
Sanwo-Olu said Lagos must be viewed not merely as a large consumer market but as a platform for production, innovation, regional trade and international investment.
He stressed that sustained capital investment and business-friendly policies would be necessary to attract investors and maintain the state’s economic competitiveness.
Lagos Target Follows Nigeria’s $1 Trillion Ambition
Lagos’ long-term economic ambition comes as the Federal Government pursues a separate target of growing Nigeria’s economy to $1 trillion by 2030. President Bola Tinubu announced the national target at the Nigeria Economic Summit in 2023, during the first year of his administration.
However, the World Bank warned in its May 2025 Nigeria Development Update, titled Building Momentum for Inclusive Growth, that Nigeria’s economic growth rate would need to increase substantially to achieve the target within the proposed timeframe.
The institution identified agriculture, manufacturing and consumer-focused services as important labour-intensive sectors that could expand employment and improve income distribution. It also acknowledged reforms such as petrol subsidy removal and foreign exchange rate unification, while warning that structural weaknesses and governance challenges could limit their benefits.
Financial Derivatives Company Managing Director Bismarck Rewane has also questioned whether Nigeria could achieve the $1 trillion target within the administration’s five-to-six-year timeframe.