The Central Bank of Nigeria has reduced its benchmark interest rate from 26.5 per cent to 23 per cent, signalling a shift in monetary policy as inflation moderates.
The Central Bank of Nigeria (CBN) has cut its benchmark interest rate by 350 basis points to 23 per cent, following a meeting of its Monetary Policy Committee in Abuja on Tuesday.
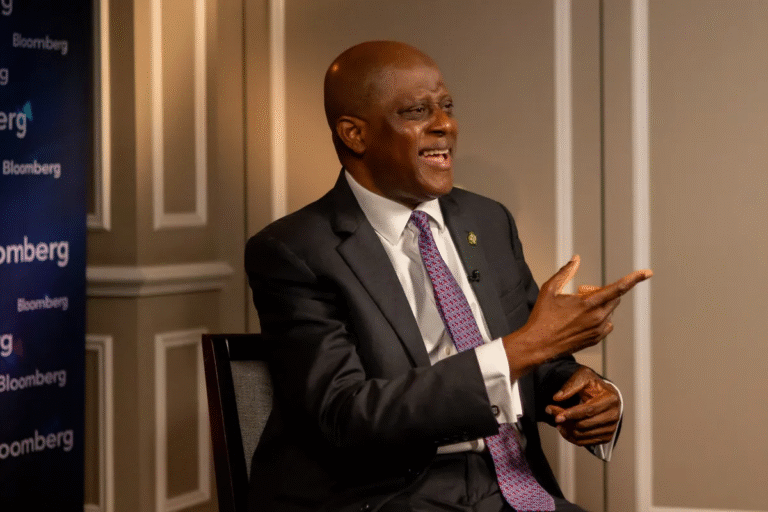
CBN Governor Olayemi Cardoso announced the decision at the conclusion of the committee’s 307th meeting on September 22, 2026.
“The Committee decided as follows: reset the monetary policy rate to 23 per cent,” Cardoso said.
The reduction takes the Monetary Policy Rate (MPR), the central bank’s principal policy interest rate, down from 26.5 per cent.
The decision comes after the committee maintained its rate at its two previous meetings. It follows an earlier 50-basis-point reduction announced in February 2026.
Inflation slowdown provides room for rate reduction
The rate cut comes against the backdrop of easing inflation, which has been a central consideration for monetary policymakers.
Nigeria’s headline inflation rate declined marginally to 15.39 per cent in August 2026, compared with 15.43 per cent in July, according to the latest Consumer Price Index report released by the National Bureau of Statistics.
The August reading marked the third consecutive monthly decline following a period of three successive monthly increases.
The moderation in inflation provides the backdrop for the MPC’s latest decision, although the available announcement does not detail the committee’s full assessment of price pressures, exchange-rate conditions or the outlook for economic growth.
What the rate cut means for businesses and borrowers
The MPR serves as a key reference point for interest rates across Nigeria’s financial system.
A reduction can influence banks’ lending and deposit rates, the cost of borrowing for businesses and households, and returns on interest-bearing investments.
However, the adjustment does not automatically translate into an equivalent reduction in commercial bank lending rates. The extent and timing of any changes will depend on banks’ funding costs, credit risks, liquidity conditions and broader market developments.
For businesses, lower borrowing costs could provide some relief if the reduction feeds through to lending rates. For savers and investors, the implications will depend on how banks and other financial institutions adjust the returns offered on deposits and other instruments.
The MPC’s latest decision therefore marks a significant change in the policy rate, while the effect on the wider economy will depend on how financial markets and lenders respond.
Further details of the committee’s deliberations and its assessment of the economic outlook are expected to provide additional insight into the direction of monetary policy.